Independent Contractors vs Employees for Cleaning (2026 Rules)
Worker classification depends on the actual relationship, not a 1099 form or contract label. Review behavioral control, financial control and the relationship under the IRS test, plus applicable labor and state tests. The cost example below is illustrative; confirm the classification before relying on it.
 R Rashdi
·
January 23, 2026
·
15 MIN READ
Quick answer
Worker classification depends on the actual relationship, not a 1099 form or contract label. Review behavioral control, financial control and the relationship under the IRS test, plus applicable labor and state tests. The cost example below is illustrative; confirm the classification before relying on it.
Written by Rashdi, founder of CleanerHQ. Not reviewed by a tax professional or employment lawyer yet, so check with one before you act.
Independent contractors vs employees is the highest-stakes paperwork decision a cleaning business makes. Get it right and you know your true labor cost. Get it wrong and the IRS, the Department of Labor, and your state can each reclassify your workers. Under Section 3509, the back taxes land on you, not the worker.
This guide gives you the IRS control test in plain English. It covers the current status of the DOL rule, which has changed repeatedly. We date-stamp everything. You also get the true-cost math side by side, the public penalty figures, and a playbook for converting 1099 cleaners to W-2 without losing them. One note up front: this is practical guidance for owners, not legal or tax advice. Confirm your specific situation with a CPA or employment attorney.
The IRS control test in plain English
The IRS uses a common-law test with three factor groups (IRS Topic 762): behavioral control, financial control, and the relationship of the parties. No single factor decides it. The IRS weighs the whole picture. Here’s what each one means when the work is cleaning.
Behavioral control, who decides how the work gets done?
Do you set the schedule, assign the route, and require your checklist? Do you train people on your methods and tell them which products to use on which surface? Then you’re describing an employee. A real contractor decides their own methods and hours. You buy a result (“the office is clean by 6 AM”), not a process (IRS guidance on behavioral control).
The uncomfortable part for cleaning businesses: almost everything that makes service quality consistent is evidence of behavioral control. That includes SOPs, required checklists, training programs, branded uniforms, and supervision. You generally can’t have both a tightly standardized service and a 1099 workforce delivering it.
Financial control, who runs the business side?
Contractors invest in their own equipment and supplies and cover their own vehicle costs. They carry their own liability insurance and can profit or lose money on a job. They typically serve multiple clients. Do your workers show up to your jobs in your van, with your vacuum and your chemicals? Do you reimburse their expenses? Then the financial-control factor points hard at employee.
Relationship of the parties, what does the arrangement look like?
An open-ended relationship with a regular weekly schedule looks like employment. A defined project with a deliverable and an end date looks like contracting. Benefits of any kind (PTO, insurance, bonuses) point to employee. And the IRS is explicit that a contract saying “independent contractor” does not override the actual working relationship. In its words: “The substance of the relationship, not the label, governs the worker’s status” (IRS Publication 15-A). The label is the least important fact in the file.
The plain-English summary for a cleaning company: a genuine 1099 relationship in this industry usually looks like a specialist. Think of a carpet-cleaning sub with their own truck-mount, a post-construction crew that bids your overflow jobs, or a window cleaner who serves ten companies. A cleaner who works your schedule, your route, and your method, week after week, is an employee in everything but paperwork.
The DOL independent contractor rule in 2026: what’s current
The Department of Labor’s independent-contractor rule under the Fair Labor Standards Act keeps changing direction. The sequence: a January 2021 rule, a 2024 rule that replaced it, and a 2026 proposal to go back to the 2021 approach. So treat any blog post (including this one) as a snapshot, and verify at dol.gov before making decisions.
Here’s the verified status as of October 2026:
- The 2024 rule (a six-factor “economic reality” analysis adopted under the previous administration) is still technically on the books. But the DOL announced in May 2025 (Field Assistance Bulletin 2025-1) that its investigators would stop applying it in enforcement.
- In February 2026, the DOL formally proposed rescinding the 2024 rule. The proposal would replace it with the analysis from its January 2021 rule, with a few modifications. The public comment period closed on April 28, 2026. No final rule had been published in the Federal Register as of October 2026.
- The DOL’s own bulletin says the 2024 rule “remains in effect for purposes of private litigation” until further action. So courts can still apply it in private lawsuits. That’s why “the DOL isn’t enforcing it” is not the same as “it can’t be used against you.”
The practical takeaway doesn’t change with the politics. Every version of the DOL test, old or new, asks the same economic-reality questions. Does the worker depend on your business for their livelihood? Who controls the work? Who invests in the equipment? Can the worker profit or lose? How permanent is the relationship? Is the work integral to your business? Cleaning the buildings your cleaning company is contracted to clean is about as integral as work gets. Build your classification to survive every version of the test. Then the rulemaking ping-pong stops mattering to you.
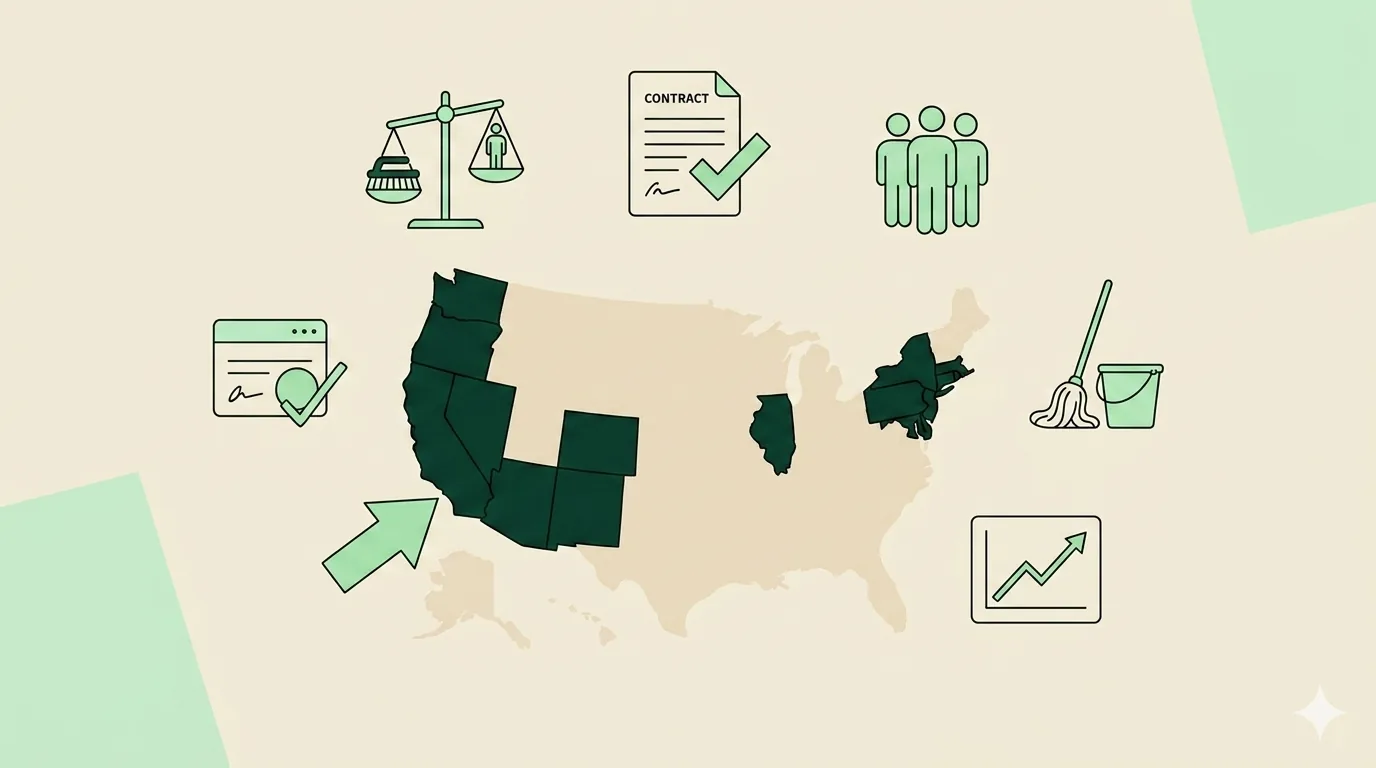
State tests are often stricter: the ABC problem
Federal tests are the floor, not the ceiling. A number of states apply some version of the ABC test. California’s is the strictest mainstream example. To call a worker a contractor there, you must prove all three (per the California Labor & Workforce Development Agency):
- A. The worker is free from your control and direction in performing the work;
- B. The work is outside the usual course of your business; and
- C. The worker has an independently established business doing this kind of work.
Read prong B again. If your business is cleaning and the worker is cleaning, you fail B, regardless of how independent they are. That’s why, in our view, 1099 cleaning crews are very hard to defend in ABC-test states. Other states use their own tests. Check your state labor and unemployment agencies as well as the IRS. You comply with the strictest test that applies to you, not the friendliest.
True cost comparison: 1099 vs W-2 (the loaded-cost table)
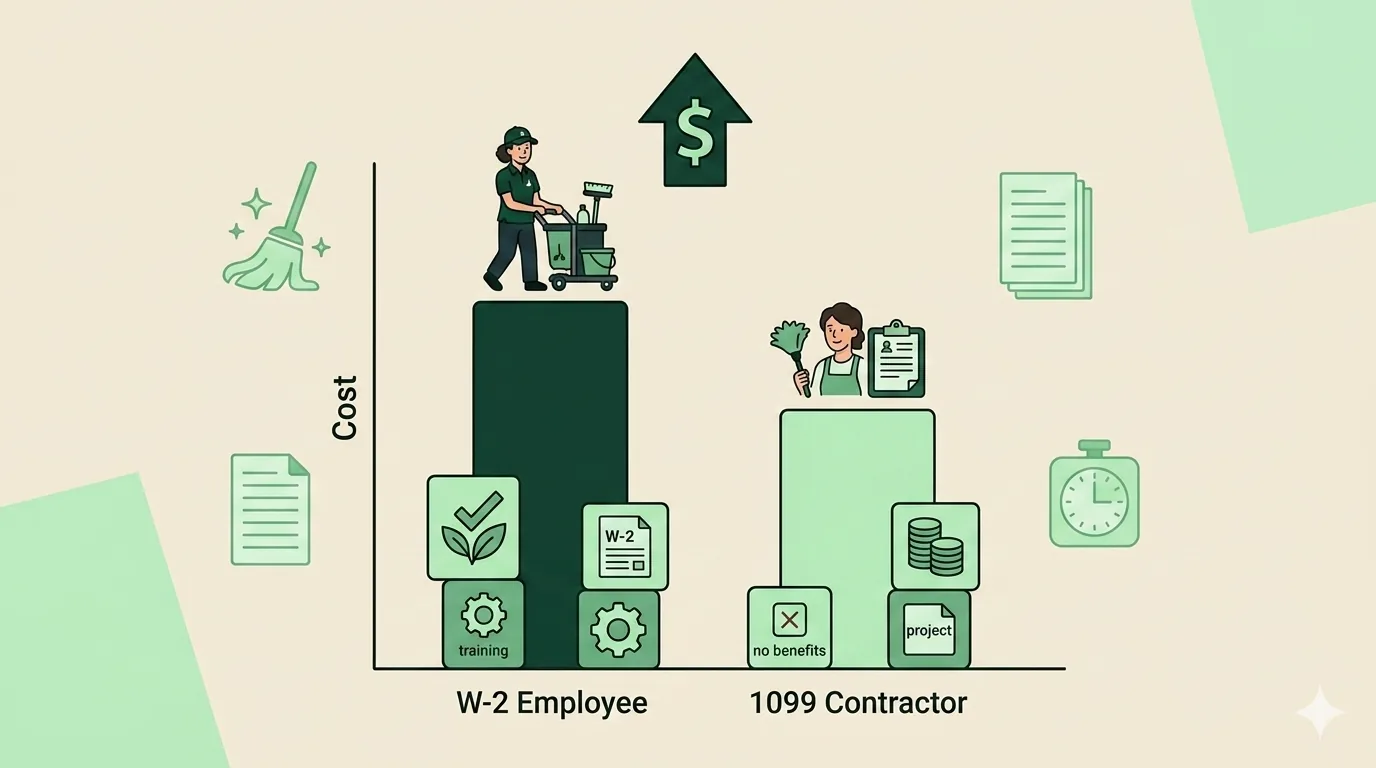
Owners often frame this as “contractors are cheaper.” That’s sometimes true, often not. Contractors price in their own taxes, insurance, and equipment. The BLS Occupational Outlook Handbook puts the national median wage for janitors and building cleaners at $17.71 an hour (May 2025). Specialist subs usually charge more per hour.
Here’s the honest side-by-side. Say you’d pay a W-2 cleaner $18/hour, and the equivalent contractor quotes $25/hour. Assume a workers comp rate of $3 per $100 of payroll (rates vary widely by state and class code). Also assume combined federal/state unemployment taxes around 2.5% on the relevant wage bases. FUTA alone is 0.6% after the state credit, on the first $7,000 of each employee’s wages, per IRS Topic 759.
| Cost line | W-2 employee | 1099 contractor |
|---|---|---|
| Base pay | $18.00/hr | $25.00/hr |
| Employer Social Security + Medicare (7.65%, IRS Topic 751) | $1.38/hr | $0, contractor pays both halves (15.3% self-employment tax, per the IRS) |
| Federal + state unemployment (~2.5% assumed) | $0.45/hr | $0 |
| Workers comp (assumed $3 per $100 payroll) | $0.54/hr | $0, contractor carries own coverage (verify their certificate) |
| Supplies & equipment | You provide | Contractor provides |
| Training & supervision time | Yours to fund | Minimal, and legally it has to stay minimal |
| Overtime liability (1.5x over 40 hrs, FLSA) | Yes | No |
| Loaded hourly cost | ~$20.40/hr (+13%) | $25.00/hr |
Add PTO, health benefits, or paid drive time and the W-2 loaded cost climbs well past that 13%. The contractor still costs more per hour in this example. What you’re buying with the W-2 premium-that-isn’t is control: your schedule, your checklist, your standard, your brand. What you’re buying with the contractor’s higher rate is zero payroll administration and capacity that scales down to zero between jobs.
The real decision rule: recurring, scheduled, supervised work belongs on W-2. That’s the core of a maid service or janitorial operation. Specialty overflow (carpet, windows, post-construction surge) is where genuine 1099 relationships live. Most healthy cleaning companies run both.
One more 2026-relevant paperwork note: the 1099-NEC reporting threshold is no longer $600. Federal law raised it to $2,000 in annual payments starting with 2026. The IRS says it may be adjusted for inflation beginning in 2027. So check the IRS instructions for Form 1099-NEC for the current figure when you file. The threshold only governs the form. Contractors owe tax on every dollar regardless.
Misclassification penalties: the public numbers
When the IRS reclassifies your “contractors” as employees, the bill stacks. The public framework (26 U.S.C. § 3509(a), for unintentional misclassification where you filed 1099s):
- 1.5% of the wages paid (for federal income tax that wasn’t withheld, § 3509(a)(1)), plus
- 20% of the employee’s share of Social Security and Medicare that wasn’t withheld, plus
- 100% of the employer’s share of FICA (IRS VCSP FAQ: the full 6.2% + 1.45%) you never paid. This one is yours in full, plus
- Interest, and failure-to-file/failure-to-deposit penalties on top.
If you never filed 1099s at all, the first two rates double (3% and 40%, under § 3509(b)). If the IRS finds intentional disregard, Section 3509’s reduced rates disappear entirely (§ 3509(c)). The trust fund recovery penalty (equal to the unpaid trust fund taxes, assessable against you personally) comes into play. Criminal exposure is also possible.
The DOL side is separate and additive. It includes back wages for minimum-wage and overtime violations going back two years (three if willful). It also includes liquidated damages that can double the back-wage figure (DOL FLSA Handy Reference Guide). State agencies stack their own per-worker fines, unemployment-insurance assessments, and workers comp premiums on top. Misclassified workers can also sue, including as a class.
Here are common audit triggers worth knowing. A “contractor” files for unemployment benefits after you stop using them. Someone with no coverage makes a workers comp claim. A worker files a Form SS-8 asking the IRS to rule on their own status. Or a routine state UI audit comes up.
If you realize you have a problem, the IRS Voluntary Classification Settlement Program (VCSP, Form 8952) lets eligible businesses reclassify workers prospectively. It also lets them settle the past for just over 1% of the prior year’s payments to those workers. That’s 10% of the tax figured at the reduced Section 3509(a) rates. It comes to about 1.07% of pay up to the Social Security wage base, per the IRS VCSP FAQ. You pay no interest or penalties. That’s dramatically cheaper than losing an audit. (The live IRS pages for Section 3509, SS-8, and VCSP have the current details. Your CPA will know the fit.)
Converting 1099 cleaners to W-2 without losing them
Most owners who run this conversion fear a walkout. We think the right math and the right framing make that much less likely. Take-home pay and predictability tend to matter most, and W-2 status can improve both. The playbook:
1. Do the rate translation honestly. A contractor at $25/hr pays both halves of FICA (15.3% self-employment tax, per the IRS) and buys their own coverage. A W-2 offer at $20-21/hr comes with workers comp, unemployment coverage, overtime eligibility, and half their FICA paid by you. It can come out equal or better in take-home pay. Run the numbers for your own rates. Show the math side by side on one page. Don’t ask them to trust you.
2. Time it to a quarter boundary. Clean payroll-tax quarters (January 1, April 1, July 1, October 1) make the accounting simpler for both sides. Your payroll provider and CPA will thank you. If you’re settling the past via VCSP, sequence that first.
3. Make the offer about what they gain. The script that works: “The rules around contractor cleaning crews have tightened. I want you on a footing that protects both of us. Here’s the offer: $20.50 an hour on W-2, workers comp coverage if you’re ever hurt on a job, unemployment protection, and overtime at time-and-a-half. And you stop owing quarterly self-employment tax. Here’s the take-home comparison.”
4. Expect to keep the true specialists as contractors. The carpet sub with three other clients and a truck-mount doesn’t convert, and doesn’t need to. Conversion is for the people who were employees all along.
5. Paper the new relationship properly. Offer letter, W-4, I-9, state new-hire reporting, workers comp policy update, and background checks run compliantly. Budget the admin time: onboarding a converted crew of five is a weekend of paperwork, not an afternoon.
The deeper upside: W-2 crews can be trained, scheduled, branded, and held to your standard. That’s the whole growth model of a well-hired cleaning team. Conversion isn’t a compliance tax. It’s the prerequisite for building a company instead of a referral network.
Running compliant W-2 field ops
Saying yes to W-2 means saying yes to wage-and-hour mechanics: accurate hours, overtime at 1.5x past 40 (FLSA), and records that survive an audit. Paper timesheets and “I think I left around 4” texts are how compliant intentions become DOL findings.
This is where the operational tooling earns its keep. CleanerHQ’s GPS clock-in records the time, the job, and a location check for each crew clock-in. It flags unusual entries for your review before you approve the hours. That’s the kind of record a wage-and-hour inquiry asks for. GPS time tracking also closes the other compliance gap: paying hours that never happened. If you’re converting a crew this quarter, create your account (free for 14 days, no card: you plus 2 cleaners). That way, you can review crew hours before they reach payroll. It’s one piece of a complete cleaning business software platform.
Calendar two adjacent obligations now rather than discover them later. First, payroll tax deposits run on a monthly or semiweekly schedule (IRS Publication 15; a payroll provider can automate this). Second, if you keep any genuine contractors, your own quarterly estimated taxes and their 1099-NECs each January still apply. Meanwhile, W-2 wages, employer payroll taxes, and workers comp premiums are all deductible business expenses (IRS Publication 334). See the full list of cleaning business tax deductions.
Frequently Asked Questions
Can a house cleaner be an independent contractor?
Yes, but only if the relationship is genuinely independent: the cleaner controls their own methods and schedule, brings their own supplies and equipment, carries their own insurance, can profit or lose money, and typically serves multiple clients. A cleaner who works your weekly route, follows your checklist, and uses your products fails the IRS control test and should be a W-2 employee.
What is the IRS test for independent contractor vs employee?
The IRS common-law test weighs three factor groups: behavioral control (who directs how, when, and with what methods work gets done), financial control (who invests in equipment, who can profit or lose), and relationship of the parties (permanency, benefits, how integral the work is). No single factor decides; a contract labeled “independent contractor” does not override the actual relationship.
How much more does a W-2 cleaning employee cost than a 1099 contractor?
Employer Social Security and Medicare alone add 7.65% (IRS Topic 751). Add unemployment taxes and workers comp, and in our worked example an $18/hour cleaner lands around $20.40 fully loaded, about 13% above the wage, before benefits. Contractors avoid those line items but usually bill higher rates, because they cover both halves of FICA (IRS self-employment tax) and their own insurance.
What are the penalties for misclassifying cleaning employees?
For unintentional misclassification with 1099s filed, IRS Section 3509 assesses 1.5% of wages plus 20% of the employee’s unwithheld FICA share, plus 100% of the employer’s FICA share, plus interest. Rates double if no 1099s were filed. Under the FLSA, the DOL can recover two years of unpaid minimum wage and overtime (three if willful) plus an equal amount in liquidated damages (DOL FLSA Handy Reference Guide), and your state may add its own penalties.
Do I need to send my cleaning contractor a 1099?
For 2026, the federal threshold for generally reportable nonemployee compensation is $2,000. Exceptions and payment-method rules can apply; review the IRS instructions. The form threshold does not decide employee status or whether income is taxable.
What is the current DOL independent contractor rule?
As of October 2026, the DOL had stopped applying the 2024 six-factor rule in its own investigations (Field Assistance Bulletin 2025-1) and, in February 2026, formally proposed replacing it with the analysis from its January 2021 rule; no final rule had been published. The 2024 rule could still appear in private lawsuits until rescission is final. The rule keeps changing, so verify the current status at dol.gov before relying on it.

Written by
Rashdi has spent 15+ years building and managing enterprise software, and has worked with US cleaning businesses since 2006. He founded CleanerHQ.